
Legal Insurance: Affordable Protection for Legal Fees and Advice
A single legal dispute can become expensive long before anyone steps into a courtroom. An initial lawyer consultation, a formal letter, court filing fees, expert opinions, and possible appeal costs can add up quickly. For many households, that cost is enough to delay getting advice or to give up on a valid claim.
Legal insurance, also called legal expenses insurance, is designed to reduce that pressure. It helps cover the cost of legal advice, lawyer fees, court costs, and related expenses when a covered dispute arises. The goal is simple: make it easier to defend your rights without facing the full financial burden alone.
This article is for general information only and is not legal or financial advice. Policy terms vary, so always read the contract and ask a qualified adviser if a dispute is already developing.

What legal insurance actually covers
Legal insurance pays for certain legal costs when a covered dispute falls within the policy. In Germany, this type of cover is often known as Rechtsschutzversicherung. It is usually modular, which means the policy may cover only selected areas of life unless broader protection is purchased.
Typical covered costs may include:
Lawyer fees within the policy limits
Court fees
Costs for expert witnesses, if required and covered
Mediation costs, where included
Legal advice by phone or online
Opponent’s legal costs, if a court orders payment
Appeal costs, if the insurer approves the appeal
The exact cover depends on the contract. Some policies offer quick legal advice for minor questions. Others help fund formal disputes that go to court. Good policies explain both the legal areas covered and the cost limits that apply.
Common areas include private legal protection, traffic legal protection, employment legal protection, and rental or property legal protection. Each serves a different purpose.
Private legal protection may help with consumer disputes, compensation claims, or conflicts after a purchase. Traffic legal protection may help after a road accident or disagreement with an insurer. Employment legal protection can support disputes about dismissal, warnings, or unpaid wages. Rental legal protection may help tenants or landlords with rent increases, deposits, repairs, or termination notices.
Legal insurance does not mean every legal matter is paid for automatically. Insurers check whether the dispute fits the policy terms. They may also review whether the case has reasonable prospects of success before approving funding for formal legal action.
That may sound restrictive, but it is also what keeps premiums within reach. The insurer agrees to carry a defined risk. The policyholder gets cost protection for the legal areas most likely to affect daily life.
Why everyday legal help can be worth insuring
Many people think of legal disputes as rare events. Serious lawsuits may be uncommon, but smaller conflicts happen more often than expected. A landlord refuses to return a deposit. A used car has hidden defects. An employer issues a sudden dismissal. A travel provider rejects a refund. A neighbour dispute becomes formal. An online purchase arrives damaged, and the seller stops responding.
Not every case needs a court hearing. In fact, early legal advice often prevents a dispute from getting worse. A clear lawyer’s letter can create movement where repeated private messages have failed. A brief consultation can show whether a claim is worth pursuing. Mediation can help both sides reach a settlement without a long process.
That early access matters. Without cover, people may hesitate before booking advice because they worry about the bill. With legal insurance, the decision can become easier. The question changes from “Can I afford to ask?” to “Is this covered, and what is the next proper step?”
Legal insurance also helps create balance. In some disputes, the other side may be a company, landlord, employer, insurer, or institution with experience handling claims. A private individual may feel outmatched. Covered legal support can make the process less intimidating.
Good cover can also protect against the risk of losing. In civil disputes, the losing party may have to pay court costs and, in some cases, the other side’s legal costs. That risk can stop people from making valid claims. Insurance can reduce that barrier, provided the claim is covered and approved.
What to check before choosing a policy
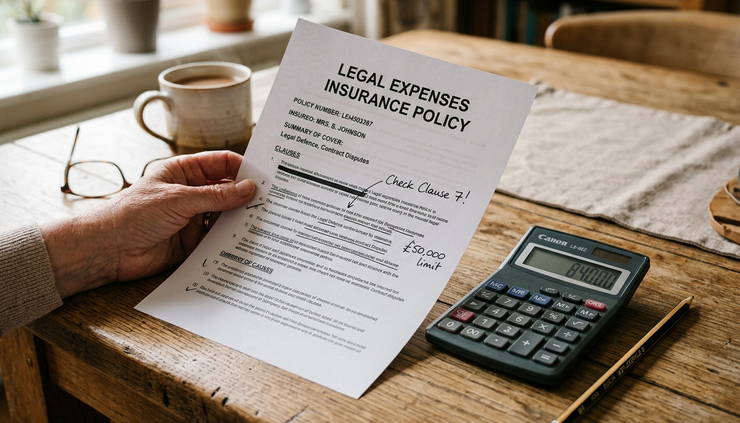
The most important part of any legal insurance policy is not the headline promise. It is the fine print. A policy can look broad at first glance but still exclude the type of dispute most relevant to you.
Start by checking which legal areas are included. A person who rents their home may care about tenant protection. A frequent driver may need traffic protection. Someone in a high-conflict workplace may value employment cover. A homeowner may need property-related protection rather than tenant cover.
Then look at the waiting periods. Many legal insurance policies do not cover disputes that already exist or begin immediately after the policy starts. Waiting periods are common, especially for employment, rental, and contract disputes. This prevents people from buying cover only after trouble has already appeared.
Next, review the sum insured. This is the maximum amount the insurer will pay for a covered matter. Higher limits may be useful for complex cases, appeals, or disputes with expert evidence. Also check whether cover applies only in Germany, across Europe, or further abroad.
The deductible matters too. In German policies, this is often called the Selbstbeteiligung. A higher deductible can reduce the premium, but it also means you pay more yourself when a case arises. The right level depends on whether you prefer lower ongoing costs or lower costs at the time of a claim.
Pay attention to lawyer choice. Some policies allow free choice of lawyer within certain rules. Others encourage or require approved legal service providers, especially for initial advice. Free choice can be valuable if you already trust a particular lawyer or need a specialist.
A helpful comparison looks like this:
Policy feature | Why it matters |
Covered legal areas | Determines whether the disputes most common in your life are included |
Waiting period | Shows when protection actually begins |
Deductible | Affects the amount you pay when making a claim |
Sum insured | Sets the maximum support available for a covered dispute |
Lawyer choice | Decides how freely you can select legal representation |
Mediation cover | Can help solve disputes before court |
Exclusions | Limits protection for certain topics or events |
Also check cancellation rules, claim reporting requirements, and whether advice hotlines are included. A low premium is attractive, but the cheapest policy may not be useful if it leaves out the risk you actually face.
What legal insurance usually does not cover
Legal insurance is practical, but it has limits. Understanding those limits helps avoid disappointment later.
Most policies exclude disputes that started before the policy began. If a landlord has already sent a termination notice or an employer has already announced dismissal, buying cover afterwards will usually not help with that specific matter. The insured event must normally occur during the active policy period and after any waiting period.
Some areas are commonly excluded or restricted. These may include divorce, inheritance disputes, construction projects, investment losses, business activities, or intentional criminal acts. Some policies offer limited advice for certain excluded areas, but not full court cost protection.
Contract wording also matters for timing. In some cases, the key question is not when the dispute becomes serious, but when the first event leading to the dispute occurred. For example, if a faulty contract was signed before the policy started, later conflict may still be treated as pre-existing.
Insurers may also refuse to fund a case if there is no reasonable chance of success. This does not mean the insurer decides the law on its own. It means the insurer may ask for a legal assessment before paying for formal proceedings. Some contracts include procedures for challenging a refusal, such as a lawyer’s opinion or another review process.
There are also behavioural duties. Policyholders normally need to report claims promptly, avoid unnecessary costs, and get approval before taking expensive legal steps. Skipping these steps can create problems with reimbursement.
This is why legal insurance works best as prevention, not damage control. It is most useful when bought before a conflict appears.

When legal insurance makes the most sense
Legal insurance is not essential for everyone, but it can be a sensible choice when legal disputes would cause real financial stress or when your life includes areas where conflict is possible.
It often makes sense for tenants who want support with deposit, rent, repair, or termination issues. It may also suit drivers, especially where daily commuting, shared vehicles, or regular long-distance travel increase the chance of traffic disputes. Employees may value cover where workplace conflict would be costly to challenge. Families may want access to legal advice when consumer, travel, school, or housing issues arise.
It can also help people who simply prefer certainty. Insurance converts the risk of a large unpredictable bill into a regular premium plus any deductible. That can make household budgeting easier.
Before buying, it helps to ask a few practical questions:
Which legal disputes would affect my life most?
Could I afford lawyer and court costs without support?
Do I already have some legal help through a union, tenants’ association, motoring club, or professional body?
Which areas do those memberships not cover?
Would I prefer broad cover or only protection for traffic, work, or housing?
Am I comfortable with the deductible?
Some people already have partial protection. A trade union may support employment disputes. A tenants’ association may provide housing advice. A motoring club may assist with road-related legal issues. These can be useful, but they may not replace a full legal expenses policy. Check the scope before assuming you are covered.
The best policy is not always the one with the longest feature list. It is the one that fits your real risks, uses clear terms, and offers support in situations where you would genuinely seek legal help.
How to use legal insurance when a dispute starts
When a legal issue appears, do not wait too long. Early action can preserve evidence, meet deadlines, and prevent extra costs.
Start by collecting documents. Keep contracts, emails, letters, invoices, photos, notices, and chat records. Write a short timeline while the facts are fresh. Include dates in a clear format, such as 14.10.2026, and note who said or sent what.
Next, contact the insurer before instructing a lawyer for paid work, unless urgent deadlines make that impossible. Many policies require a claim number or cover confirmation before costs are incurred. Explain the issue clearly and ask which steps are approved.
A simple first report should include:
Your policy number
The type of dispute
The date the problem began
The other party involved
The outcome you want
Any deadlines already known
Copies of key documents
If the insurer offers a legal advice hotline, use it for early guidance. It can help clarify whether the matter is covered and what evidence is useful. If the case needs a lawyer, ask whether you can choose one or whether the insurer recommends a provider.
Avoid escalating the dispute emotionally. Do not send threats, admit fault, agree to settlement terms, or sign documents before getting advice. Short, factual communication is safer.
If the insurer rejects cover, ask for the reason in writing. Compare it with the policy wording. If the refusal seems unclear, request an explanation of the relevant clause and any review options under the contract.

The key takeaway
Legal disputes are rarely welcome, but they become harder when cost fears block early advice. Legal insurance can make professional support more accessible by covering approved lawyer fees, court costs, and related expenses for everyday disputes or formal litigation.
The value comes from choosing well before a problem starts. Look closely at covered areas, waiting periods, deductibles, exclusions, and lawyer choice. Match the policy to the disputes most likely to affect your life, not to a generic promise of protection.
Peace of mind does not come from assuming every legal problem is covered. It comes from knowing what support you have, when it applies, and how to use it when the unexpected happens.


Comments